改善
KAIZEN 改善 • Continuous Improvement
KAIZEN COCKPIT
// THEME:
// LOCALIZATION MATRIX
LOGIN TO TERMINAL INITIALIZE REGISTRATION
TOKYO QUANT ENGINE • SPATIAL & TRIANGULAR

INSTITUTIONAL HIGH-FREQUENCY ARBITRAGE PROTOCOL

ENGINEERED IN TOKYO, JAPAN • MICROSECOND CROSS-EXCHANGE & 3-ASSET LOOP ROUTING • METHOD A SHA-256 & BSCSCAN VERIFIABLE PROOF

// PHILOSOPHY & FOUNDATION

WHAT IS KAIZEN (改善) ARBITRAGE PROTOCOL?

KAIZEN (改善) represents the Japanese corporate ethos of continuous micro-improvement. In Web3 financial markets, market-neutral yield is executed through microsecond quantitative optimization of price discrepancies across liquidity books[cite: 1, 2].

Headquartered in Tokyo, Japan, KAIZEN Arbitrage Protocol operates as an institutional-grade Web3 High-Frequency Trading (HFT) infrastructure connecting 10 global liquidity hubs (Binance, Bybit, OKX, KuCoin, Bitget, Gate.io, Kraken, Coinbase, HTX, MEXC) with zero directional market exposure[cite: 1, 2].

ABSOLUTE ZERO DIRECTIONAL LOSS

Our proprietary Off-Chain Order Matching Engine guarantees trades execute only when orderbook spreads satisfy positive net yield parameters[cite: 1, 2].

10 GLOBAL CEX EXCHANGES
90 ARBITRAGE ROUTES
<15ms TOKYO HFT LATENCY
DUAL SHA-256 & BSC PROOF
// MATHEMATICAL DISCREPANCY ANALYSIS

THE SCIENCE OF ARBITRAGE SPREADS

Orderbook Fragmentation

Regional latency and local order flows cause temporary price divergences between ask prices on Source exchanges and bid prices on Target exchanges[cite: 2].

Microsecond Execution

Automated routing engine connects via WebSocket feeds to simulate dark pool liquidity routes and capture micro-second spread gaps instantly[cite: 1, 2].

Mathematical Risk Immunity

Because buying and selling occur simultaneously across connected asset pools, overall portfolio exposure to market volatility remains 100% neutral[cite: 1, 2].

// FORMULA: NET ARBITRAGE YIELD EQUATION
$$\text{Net Yield} = \Big[ (P_{\text{Target\_Bid}} - P_{\text{Source\_Ask}}) \times V_{\text{Volume}} \Big] - \Big( Fee_{\text{Maker}} + Fee_{\text{Taker}} + \text{Slippage} \Big)$$[cite: 2]

// Automated execution triggers only when Net Yield > 0[cite: 2].

// CROSS-EXCHANGE ROUTING

MODE 01: SPATIAL ARBITRAGE TERMINAL

Exploiting real-time price discrepancies between two distinct centralized liquidity exchanges[cite: 1, 2].

// DUAL EXCHANGE PIPELINE

Binance ➔ Bybit Spatial Flow

When Bitcoin (BTC) trades at $95,100 on Binance (Source) and $95,280 on Bybit (Target), Spatial Mode buys on Binance and sells on Bybit simultaneously[cite: 2].

Step 1: Source Buy (Binance) $95,100.00 USDT
Step 2: Target Sell (Bybit) $95,280.00 USDT
Gross Yield Spread: +$180.00 USDT (+0.189%)

90 Dynamic Spatial Routes

Configure any dynamic pair between top 10 global exchanges to execute spatial scans on demand.

START SPATIAL SCANNING
🔺 SINGLE-EXCHANGE 3-ASSET CROSS-PAIR LOOP

MODE 02: TRIANGULAR LOOP ARBITRAGE

Executing a closed 3-step asset conversion loop inside a single liquidity node (USDT ➔ BTC ➔ ETH ➔ USDT) to capture cross-pair imbalances with zero network delay[cite: 1, 2].

01

ENTRY: BASE TO ASSET A

User allocates USDT capital balance to purchase Bitcoin (BTC) on the primary orderbook ask side[cite: 2].

USDT ➔ BTC (Leg 1)
02

CROSS-CONVERT: ASSET A TO B

HFT Bot instantly converts BTC into Ethereum (ETH) via the ETH/BTC pair, capturing micro-second cross-spread gaps.

BTC ➔ ETH (Leg 2)
03

SETTLEMENT: ASSET B TO BASE

ETH is sold back to USDT on the ETH/USDT orderbook, completing the closed loop with net yield settlement.

ETH ➔ USDT (Leg 3)
100% AUTOMATED TRIANGULAR ROUTING Zero Slippage Friction • Single Exchange Dark Pools • Dual Cryptographic Proof
ACTIVATE TRIANGULAR LOOP
// GLOBAL LIQUIDITY MATRIX

10 CONNECTED CEX EXCHANGES

BINANCE WebSocket Active
BYBIT WebSocket Active
OKX WebSocket Active
KUCOIN WebSocket Active
BITGET WebSocket Active
GATE.IO WebSocket Active
KRAKEN WebSocket Active
COINBASE WebSocket Active
HTX WebSocket Active
MEXC WebSocket Active
// FLEXIBLE EXECUTION PIPELINES

TRADING EXECUTION OPTIONS

// MANUAL OPTION 01

1-Hour Manual Scan

Traders execute micro-arbitrage trades manually. Capital locks for 1 hour while liquidity routes scan micro-spreads.

Requires Hourly Clicks
// MANUAL OPTION 02

24-Hour Manual Scan

Extended daily arbitrage execution cycle. Allocates capital for 24 hours with consolidated single-payout settlement.

24-Hour Single Cycle
// AUTOMATED QUANT OPTION

7-Day Automated AI Bot

Eliminates manual clicks. Trades execute continuously for 7 days auto-compounding yields without daily user intervention.

AI BOT AUTOMATION FEE: 100% FREE ($0 USD) • INCLUDED
// TOKYO INFRASTRUCTURE ARCHITECTURE

ROPPONGI HILLS TOKYO DATA NODE

Colocated adjacent to Tokyo Equinix TY3 financial data centers to guarantee ultra-low latency routing[cite: 2].

TY3 EQUINIX COLOCATION

Direct fiber cross-connects to primary CEX liquidity gateways in Tokyo.

JST TIMEZONE LOCK

Backend PHP & MySQL timestamp synchronization locked to Asia/Tokyo timezone.

MICROSECOND WEBSOCKET

Real-time streaming feeds providing instant orderbook depth updates[cite: 2].

DARK POOL OTC

Executing high-volume loop conversions without triggering public slippage[cite: 2].

// TOKYO EXECUTIVE GOVERNANCE & FOUNDER MANIFESTO

TOKYO QUANT LEADERSHIP & VISION

Pioneered by Tokyo academic quantitative researchers, market-microstructure experts, and algorithmic HFT architects[cite: 1, 2].
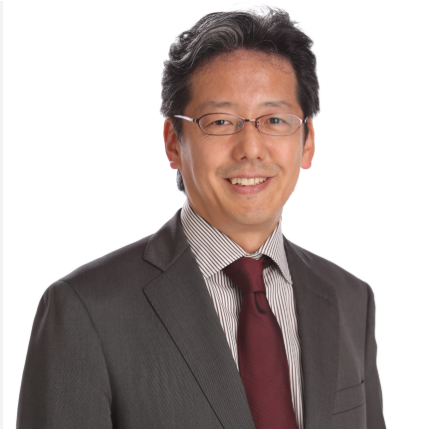
CHIEF EXECUTIVE
Prof. Katsuhiko Okada
Prof. Katsuhiko Okada FOUNDER & CHIEF EXECUTIVE OFFICER

Academic Quantitative Finance Professor & Arbitrage Pioneer from Tokyo, Japan. 20+ years of high-frequency orderbook research & quantitative desk management[cite: 1, 2].
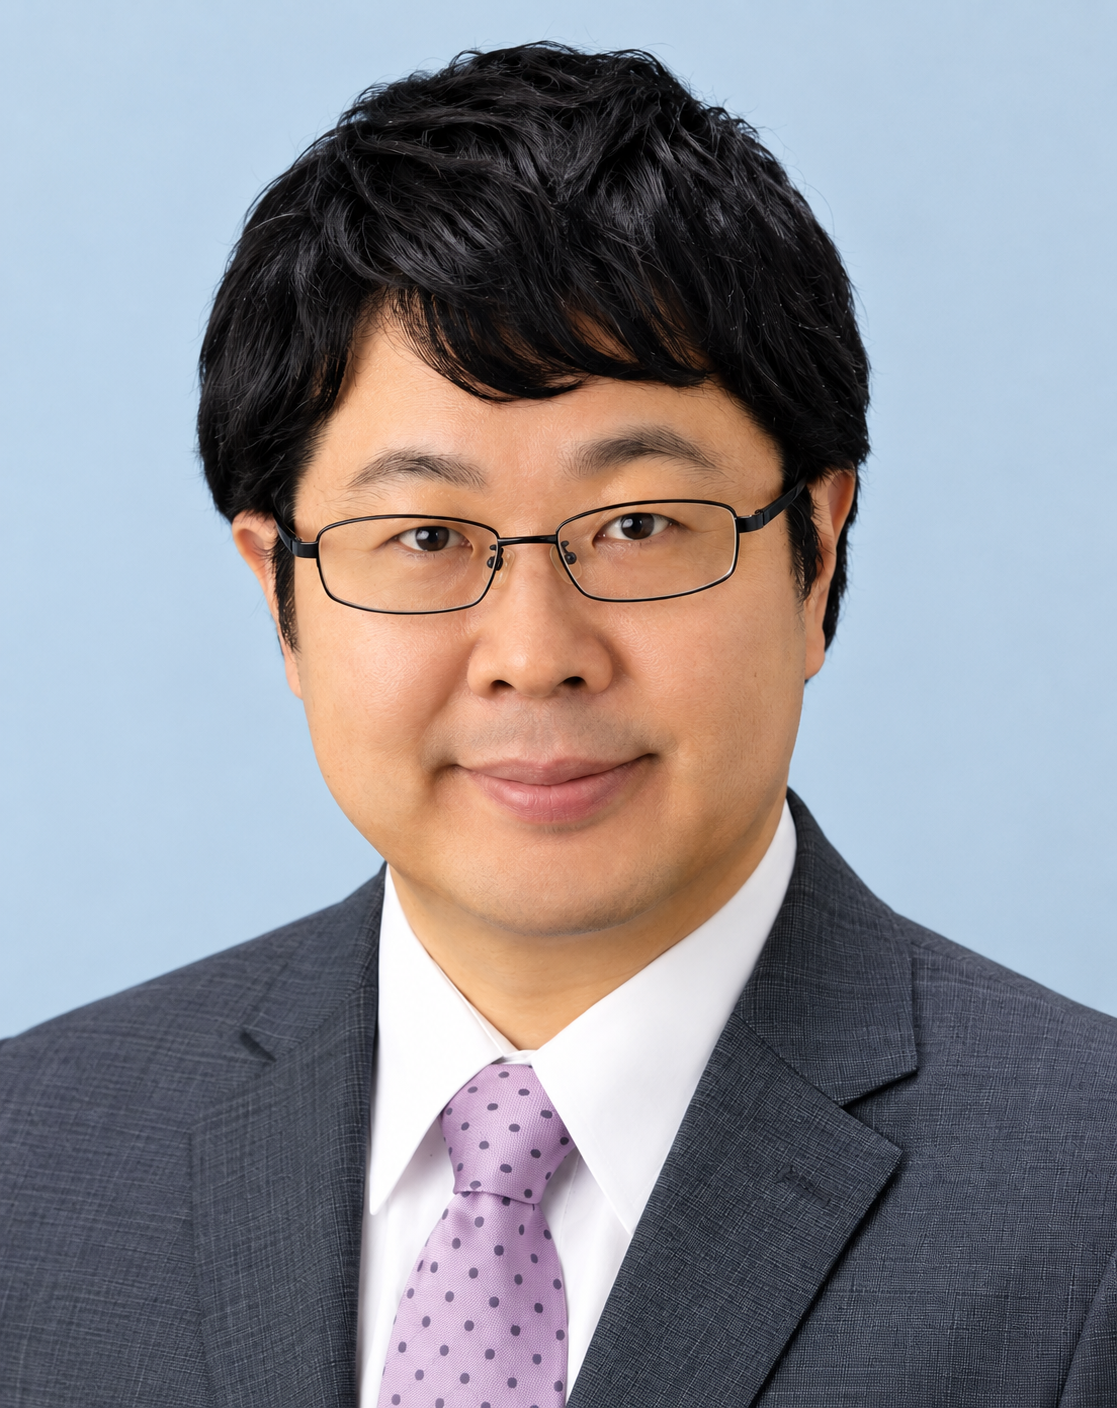
Takanori Adachi
Takanori Adachi CHIEF TECHNICAL OFFICER

Tokyo-based HFT System Architect. Specialist in sub-millisecond Order Matching Engine development, WebSocket Streaming, and Dual Cryptographic Proof frameworks[cite: 1, 2].
Seiji Watanuki
Seiji Watanuki HEAD OF ARBITRAGE QUANT SYSTEMS

Quantitative Research Lead from Tokyo, Japan. Expert in 3-Leg Triangular Cross-Pair Spread Models and Zero-Directional-Risk Liquidity Pool Optimization[cite: 1, 2].

FOUNDER'S MISSION & VISION

"THE EVOLUTION OF KAIZEN: DEMOCRATIZING INSTITUTIONAL ALGORITHMIC SUPERIORITY"

"For decades in Tokyo's financial district, institutional Wall Street trading desks and high-frequency quantitative funds retained exclusive access to market-neutral triangular arbitrage profits[cite: 1, 2]. Small retail participants were left exposed to extreme market volatility and directional risk."

"KAIZEN (改善) was born out of a single fundamental mission: to engineer an automated, transparent, microsecond-latency protocol that grants global retail users equal access to zero-directional-risk arbitrage yield[cite: 1, 2]."

"We are constructing an ecosystem rooted in total cryptographic auditability via Method A SHA-256 verification and on-chain BNB Smart Chain (BscScan) ledger integrity[cite: 1, 2]. Every arbitrage cycle captured is hashed and verifiable, guaranteeing constant, microscopic improvement of our core engines for absolute capital safety and performance[cite: 1, 2]."

— PROF. KATSUHIKO OKADA (岡田 克彦), FOUNDER & CEO TOKYO, JAPAN 🇯🇵
// PUBLIC METHOD A & BSCSCAN DUAL EXPLORER

DUAL VERIFIABLE CRYPTOGRAPHIC LEDGER

Verify 64-character SHA-256 internal execution hashes and real BNB Smart Chain (BscScan) on-chain transaction hashes with exact package volume proof[cite: 1, 2].

// DYNAMIC ALGORITHMIC YIELD ESTIMATOR ($50 MULTIPLES)

STAKING PACKAGE VALUE (USD) $50
60% TRADER SHARE (EST. MIN YIELD) $2.40 / Mo
60% TRADER SHARE (EST. MAX YIELD) $4.80 / Mo
// PROTOCOL FAQ

SYSTEM OPERATIONS CLEARANCE

What is the difference between Spatial and Triangular Arbitrage?
What are the package entry and gas reserve rules?
How does the 60% / 40% trade profit split work?
How do 2X Capping and Weekly Working Income limits operate?
How is trade execution verified on BscScan and Method-A SHA-256?